Guide to Tax Payable on TPD Lump Sum Payments
If you are wondering whether you pay tax on TPD payments from super, the short answer is this: a total and permanent disability (TPD) insurance payout paid into super is generally tax-free while it stays in your super account, but if you withdraw it before your preservation age, tax may apply. But different rules may apply if TPD is paid outside super.
That difference matters more than almost anything else. In many cases, a TPD benefit paid through a super fund can include a tax-free component, a taxable component, or both. A TPD benefit paid directly from an insurance policy outside super is generally much simpler, because it is usually treated differently from a super lump sum.
That difference matters more than almost anything else.
- A TPD benefit paid through a super fund can include a tax-free component, a taxable component, or both.
- A TPD benefit paid directly from an insurance policy outside super is generally much simpler, because it is usually treated differently from a super lump sum.
The problem is that most people are told they have a “TPD payout” without being told what sort of payment they are actually receiving. That is where surprises happen. This guide explains the tax rules in plain English, when TPD payouts are taxed, when they are not, and what to check before you spend a cent.
When you have a successful claim, your TPD insurance payout is generally not considered taxable income and is tax-free. As long as you leave this money in your superannuation account until you reach retirement age.
What is a TPD Payout?
According to the Income Tax Assessment Act 1997 (ITAA 1997) a TPD lump sum payout is:
(a) An insurance benefit paid to someone suffering from ill-health, either physical or mental, and
(b) Two legally qualified medical practitioners have certified that the person’s illness or injury makes it unlikely that they will ever be able to be employed in a job for which they are qualified because of their education, experience, or training.

Is a TPD Payout Tax-Free?
If the payout comes from super
A TPD claim paid through your super fund is usually dealt with under the superannuation tax rules. That means the payment is not automatically tax-free, even though it may still be taxed at a concessional rate.
What matters is the component split on the payment summary or fund statement. In broad terms:
- The tax-free component is not taxed
- The taxable component may be taxed, depending on your age and the way the benefit is paid
In Australia, you can generally avoid paying tax on a TPD payout from super by leaving the funds in your super account until you reach preservation age.
If the payout comes from an insurance policy outside super
A TPD benefit paid directly from an insurance policy outside super is usually treated differently from a super lump sum. In practice, that often makes the tax question simpler, but it still depends on the exact structure of the policy and how the payout is made.
If you haven’t been given paperwork showing whether the payment came from super or an outside policy, get that first. Without it, you are guessing.

When Tax Can Apply to a TPD Payout
The most common tax traps are:
- TPD paid through super and treated as a superannuation lump sum
- A taxable component sitting inside the payment
- Death benefit style payments where the recipient is not a tax dependant
- Payments made before age 60, where super tax rules can be less generous
For superannuation lump sums, the ATO treats the payment differently depending on the components involved and your age when you receive the money.
- In some cases, the taxed element can be taxed at a lower rate or not at all.
- In other cases, withholding applies at the time of payment, and the final amount depends on your tax return.
That’s why two people can each receive a “TPD payout” and end up with completely different tax outcomes.
A simple way to think about it: the label on the payment doesn’t tell you the tax result. The structure does.
How to Check What Tax You’ll Pay
Before you assume your payout is tax-free, check these four things:
- Where the money came from: Was it paid through your super fund, or directly under an insurance policy?
- The payment summary or statement: Look for references to tax-free and taxable components, or a superannuation lump sum payment summary.
- Your age when you received it: Age can change the tax treatment of super lump sums.
- Whether it is a death benefit: If the payout is being treated as a death benefit, the tax outcome can change again depending on who receives it.
- If the paperwork is unclear, ask for it before the money is paid out or spent. That is much easier than trying to fix a tax problem after the fact.
- We regularly see people focus on the payout amount and ignore the tax classification. That is usually the expensive mistake.
What to Do If You Think Tax Has Been Taken Out Incorrectly
If the fund has withheld tax and you think it is wrong, take action. Start by getting:
- The payment summary
- The fund’s explanation of the components
- The date the payment was made
- Any correspondence about whether the benefit was treated as a super lump sum or a death benefit
Then check the tax return treatment. Sometimes the issue isn’t that too much tax was taken, but that the payment was misclassified from the start.
If the amount is significant, get advice before lodging anything. With TPD payouts, a small classification error can create a much bigger problem once the ATO gets involved.
Tax on TPD Payment in a Superannuation Fund
You must pay tax if you are below your superannuation preservation age (which depends on your date of birth) and withdraw funds from your TPD payout.
When you withdraw TPD funds from your superannuation, your superannuation provider will issue a PAYG summary to the Australian Tax Office, which has already deducted tax.
- The Australian government will tax you at the top rate, and you can claim some of this back on your annual tax return.
- For instance, if you have no job or other income, you will likely get some of this tax back at the end of the year.
The Actual Tax Rates on a TPD Payout Through Super (2026)
This is where most guides go vague. Here are the actual rates the ATO applies to the taxable component of a super lump sum, sourced directly from Schedule 12 of the ATO’s tax tables (effective 1 July 2026).
The rate you pay depends on two things: your age when the payment is received, and whether the taxable component is a taxed element or an untaxed element.
- Your TPD claim benefit is usually taxed at 22%, including the Medicare Levy (the taxable portion). However, your superannuation provider will apply a tax-free uplift calculation, so some of it will be tax-free.
- When you withdraw permanent disability TPD funds from a super account or roll over to another superannuation fund, this is a new tax-free component calculation.
- Every Australian with a successful TPD payment is taxed at a special rate ranging from 1% to 18%. Each can be taxed at varying rates if you have multiple super accounts and multiple TPD claims.
Taxed element of the taxable component
Your age | Amount subject to tax | Max tax rate (excl. Medicare levy) |
|---|---|---|
Under preservation age | Whole amount | 20% |
Preservation age to 59 | Up to $260,000 (low rate cap) | Nil |
Preservation age to 59 | Above $260,000 | 15% |
60 or over | Whole amount | Nil |
Untaxed element of the taxable component
Your age | Amount subject to tax | Max tax rate (excl. Medicare levy) |
|---|---|---|
Under preservation age | Up to untaxed plan cap ($1,935,000) | 30% |
Under preservation age | Above the cap | 45% |
Preservation age to 59 | Up to low rate cap ($260,000) | 15% |
Preservation age to 59 | Above $260,000, up to cap | 30% |
60 or over | Up to untaxed plan cap | 15% |
60 or over | Above the cap | 45% |
Add 2% Medicare levy on top of these rates. So a 20% rate becomes 22%, a 15% rate becomes 17%, and so on.
The low rate cap of $260,000 is a lifetime cap, not a per-payment cap. If you have previously accessed super lump sums, that amount reduces what’s left of your cap now.
For most people receiving a TPD payout through a standard industry or retail super fund, the payment will contain a taxed element, not an untaxed one. Untaxed elements are more common in certain public sector funds. If you’re not sure which applies to your fund, check the payment summary or ask the fund directly.
What is the Superannuation Preservation Age?
The tables above refer to “preservation age” a lot, and it matters because it’s the dividing line between cheaper and more expensive tax treatment. Your preservation age isn’t 65, and it isn’t 60 for everyone.
According to the ATO’s key superannuation rates, here’s how it works:
Date of Birth | Preservation Age |
Before 1 July 1960 | 55 |
1 July 1960 – 30 June 1961 | 56 |
1 July 1961 – 30 June 1962 | 57 |
1 July 1962 – 30 June 1962 | 58 |
1 July 1963 – 30 June 1963 | 59 |
From 1 July 1964 | 60 |
If you were born after 30 June 1964, your preservation age is 60. That’s the case for many people currently making TPD claims.
Why this matters for your payout: If you receive a TPD benefit before you reach your preservation age, the taxable component is taxed at 20% (plus Medicare levy).
- Once you reach preservation age, you can withdraw $210,000 tax-free, with anything above that taxed at 15%.
- If you are over 60, all superannuation withdrawals are tax-free.

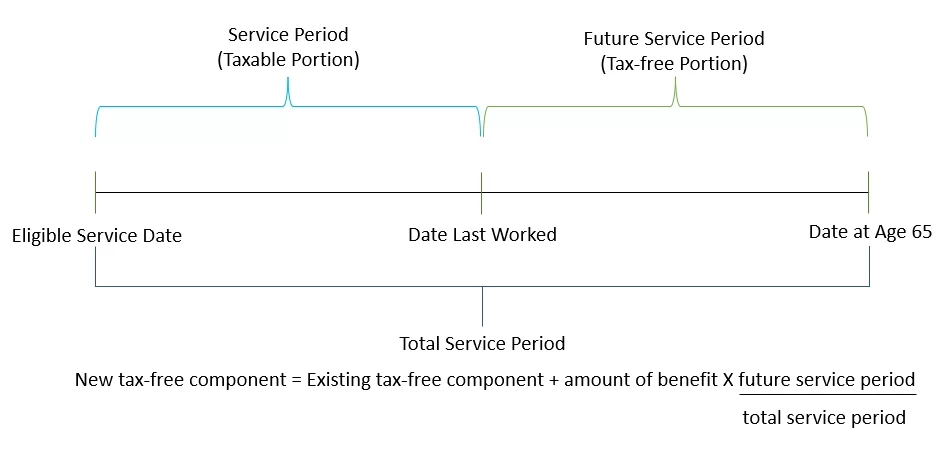
3 Factors for the TPD Tax-Free Uplift Calculation
When you withdraw TPD money before the preservation age, you may be eligible for a tax-free uplift. This calculation uses three taxable components.
- Date of birth
- Eligible service date: This is the date your superannuation account started. If you combine multiple superannuation accounts into one, the earlier eligible service date is used for calculations.
- Date last worked: This was when you ceased working due to your total and permanent disability. In most cases, it is not the date you acquired your medical condition but your job cessation date.
Basically, the time between when your super account began (the earlier start date) and your date of last work is the taxable component and is taxed at 22%. The time between your date of previous work and your preservation age is tax-free.
Please know that superannuation funds do not always calculate taxes correctly. So, it would be a good idea to speak with an experienced accountant or tax agent to confirm your tax commitment.
A Real-World Example: How the Tax Plays Out
Numbers on a page are easier to understand with a concrete scenario. Here’s how the tax calculation works for a typical TPD claimant.
Scenario: Sarah is 45. She receives a TPD payout of $350,000 through her industry super fund. The fund confirms the payment is a superannuation lump sum with:
- Tax-free component: $80,000
- Taxable component (taxed element): $270,000
Here’s what happens at tax time if she withdraws all the funds:
- The $80,000 tax-free component is not taxed. Sarah receives this in full.
- The $270,000 taxable component is taxed because Sarah is under her preservation age of 60.
- The ATO applies the 20% rate (plus 2% Medicare levy = 22%) to the full taxable amount.
- Tax withheld: approximately $59,400.
Sarah’s net receipt is roughly $290,600 from a $350,000 payout.
Now compare that to the same payout received at age 62:
- The taxable component of $270,000 would be taxed at nil (non-assessable, non-exempt income).
- Sarah would receive the full $350,000.
The difference in this example is nearly $60,000, based purely on age at the time of payment.
This example shows why seeking proper advice before the payment is processed can matter, particularly if you are close to a threshold age and there is any flexibility in the payout timing.
Typical TPD Taxable Income Calculation Errors
Many people withdrawing TPD funds are overtaxed because the incorrect time is used as the last worked date. Sometimes, superannuation funds use the date they did your calculation or the time your claim was accepted. In this situation, you can pay too much tax because they are using a later date than when you ceased working.
What To Do If You Are Overtaxed
If the super fund takes too much tax, you can claim it back at the end of the financial year, but this isn’t always the case.
Your super fund sent incorrect information to the ATO, so they must rectify the error. You should ask them for an explanation of how they calculated your tax.
What are the Lump Sum Superannuation Withdrawal Rules?
Generally, you can access the funds in your super account once you have met a condition of release, like reaching your preservation age or retirement. Once approved, you can choose to:
- Withdraw a lump sum amount
- Make a partial withdrawal
- Roll over your super balance to begin an income stream.
TPD Insurance Outside Super: A Different Tax Treatment
Not all TPD insurance sits inside a super fund. Some people hold a standalone TPD policy directly with an insurer, completely separate from their superannuation. The tax treatment here is different, and often simpler.
Lump sum disability benefits from outside super
A lump sum payment from a TPD policy held outside super is generally treated as a capital payment, not income. That means it typically isn’t included in your assessable income and isn’t subject to income tax in the same way as a super lump sum.
However, there are some important caveats:
- The policy structure matters. If the policy has any element that looks like income replacement rather than a capital disability benefit, the ATO may treat part of it differently.
- If you held the policy through a business or trust structure, the tax treatment can change significantly.
- Policies that pay ongoing monthly benefits (income protection) are taxed as income. A standalone TPD lump sum is different, but make sure you know which type of policy you have.
How to tell which type of policy you have
The simplest way is to look at your policy documents. Look for:
- References to “total and permanent disability” as a lump sum benefit
- Whether the policy is listed as a superannuation policy or a standalone policy
- The insurer’s name: if it’s your super fund paying out, it’s a super benefit; if it’s a separate insurer, it’s likely outside super
If you’re unsure, call the insurer and ask directly: “Is this benefit paid from a superannuation fund or outside super?” The answer will tell you which tax framework applies.
The bottom line: Outside-super TPD policies are generally more tax-friendly for working-age claimants, but they are also less common. Most Australians have their TPD cover bundled inside their super fund.
How to Reduce Your TPD Tax
Before withdrawing your TPD payout, you must understand your financial circumstances and tax obligations. It would be worthwhile speaking with a tax professional. Understanding the tax treatment for TPD benefits by the Australian Tax Office could save you thousands of dollars.
Summary of TPD Tax Obligations and Tax Free Uplift
Here is a simple breakdown of how tax applies to TPD payouts.
- If you are 60 or older, your TPD payout is tax-free.
- Below 60 years old, your tax commitment depends on your eligible service date, which is usually the date you joined your super fund.
- If you are below your preservation age, some of your withdrawals will be tax-free, and the balance is taxed at 22%
- If you are below 60 years old but at your preservation age, withdrawals of $ 225,000 or less are tax-free.
- If you make a lump sum withdrawal over $225,000: some of this money will be tax-free.
How Does a TPD payout impact Centrelink payments?
If you receive social security benefits and are due a successful TPD payout, you will likely want to know how they work together.
When your TPD lump sum payment is approved, your funds will be deposited into your superannuation fund account. Centrelink will disregard your superannuation account balance from their means assessment until you are in the 65.5 to 67-year age range, which is the Centrelink Age Pension period. Other Centrelink benefits will also not be impacted, like child support payments.
If you withdraw some or all of your TPD payout from your superannuation fund account, this situation changes. In this circumstance, Centrelink may consider reassessing your financial situation and adjusting your social security payments.
We recommend you seek professional financial advice for potential strategies before withdrawing your TPD funds from your superannuation account. The Centrelink claim process is typically complex, and you want to be sure you are making the best decision.
Which Income Tax Assessment Act Sections Apply to Tax Paid on TPD Lump Sum Benefits?
The following Australian legislative provisions determine tax payable on TPD benefits:
- Income Tax Assessment Act 1997 section 6-5
- Section 118-30
- section 307-145, particularly subsections 2 and 3
- Section 307-210, 215, 220(1) and 400
- Section 307-215

Common Questions About Tax on TPD Payouts
What is adjusted taxable income?
The total of the following values is known as adjusted taxable income:
- Your annual taxable income (excluding any assessable First home super saver released amount)
- Adjusted fringe benefits total
How do you calculate the eligible service date?
The eligible service date is the earlier date of either:
- Your account opening date with the super fund
- The date you began working that is related to contributions to your super account.
If in doubt, it’s best to contact your super fund to get your service date.
Why is my TPD claim taking so long?
Two significant factors in the time for TPD claim approval are:
- The complexity of the TPD claim
- The size of the payout
Insurance companies often aim to devalue large claims, which results in lengthy negotiations with TPD insurance lawyers. However, you can speed up the TPD claim process by actively pursuing the permanent disability TPD insurance company.
Is a TPD payout counted as income for Centrelink purposes?
A super lump sum can affect your Centrelink entitlements, depending on how you hold the money after payment. The lump sum itself may not be considered income in the week you receive it, but once it sits in a bank account or is invested, it can affect asset and income tests.
This is a separate issue from tax, and it is worth checking with Services Australia before the payment arrives.
What if the fund withholds too much tax?
Sometimes a super fund applies withholding at the time of payment based on the information it has. If the withholding was incorrect, you can address it through your tax return. The ATO reconciles the withholding against the actual tax liability when you lodge your tax return.
If you believe the fund has applied the wrong rate or classified the components incorrectly, raise it with the fund first. If you do not get a satisfactory response, a formal complaint through the Australian Financial Complaints Authority (AFCA) is the next step.
Do I need to declare a TPD payout on my tax return?
It depends on the source. A super lump sum that is entirely tax-free (for example, the tax-free component, or a taxed element received at age 60+) is classified as non-assessable, non-exempt income. You generally do not need to include it as assessable income on your return, but you may still need to report it. Check the payment summary from your fund, which will tell you exactly what to declare.
A standalone outside-super lump sum disability payment is also generally not assessable income. But again, check the payment summary and confirm with a tax adviser if the amount is significant.
Can I reduce the tax on my TPD payout?
You cannot reduce tax on a TPD payout through standard deductions. That’s because the ATO rules set the tax treatment of a super lump sum, and the fund applies it at source. So you cannot offset it against work-related deductions or negative-gear it the way you might with ordinary income.
What can make a difference is the timing of the payment relative to your age, and ensuring the fund has correctly classified the components. If the fund has miscategorised part of the payment, that is worth challenging.